Thursday, September 15, 2011

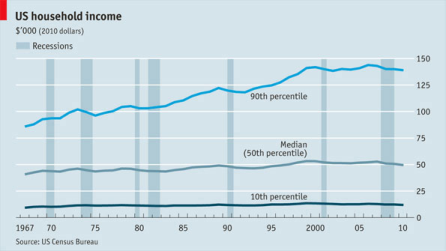
Income Groups over 40 Years


Note that if average tax rates have remained the same for the top 10%, and their income has risen--they are paying a higher proportion of the total tax burden now as compared to what they paid in 1970.

The debate is not so much that higher income earners should pay more---the issue is how much "more" is enough. 


This has real impact on markets. Fear that "surplus" income will be taken away in the future causes the investor class to take fewer risks--hence lower stock prices and lower interest rates.

This economic commentary is related to politics (political economy) and is the sole responsibility of the author and no other. It is not to be considered financial advice or a solicitation for political support.

Wednesday, September 14, 2011

Federal Income Tax Burden by Income Group


This info is from the Federal Reserve Bank of St. Louis. Link: Tax Burden at FRED for entire article. It, and the "Jeffersonian" quote from 1817 highlights the debate about "fairness" that underlies the other debate about the size of government currently raging in the USA. It is this debate and struggle that is the root of the uncertainty that is one major cause of the slowness in our economy.  Debt can only be eliminated with inflation or taxes. Spending in the long term therefore can only be offset by inflation or taxes. In either case, when government takes from one to give to another--it should be no surprise that the one who is burdened by the "taking" resists and is reluctant to "invest".

Note that the tax rate % for the highest 5% and the highest 20% has remained about the same since 1980.

Note also that the tax rate % for the other (lower) 80% has declined signficantly--with the lowest 20% actually getting more $ back from the government than they paid in. Nearly 40% are paying nothing.


Thomas Jefferson (1817) A TREATISE ON POLITICAL ECONOMY

"To take from one, because it is thought that his own industry and that of his fathers has acquired too much, in order to spare to others, who, or whose fathers have not exercised equal industry and skill, is to violate arbitrarily the first principle of association, ‘the guarantee to every one of a free exercise of his industry, and the fruits acquired by it."

Until this uncertainty is eliminated or reduced by a clear message sent by a national election, it is quite possible that economic activity may be sub-optimal.

This economic commentary is related to politics (political economy) and is the sole responsibility of the author and no other. It is not to be considered financial advice or a solicitation for political support.

Monday, August 22, 2011

Fear of Deflation/Depression do not consider All potential Fed Actions


Bernanke's 2002 Speech

http://www.federalreserve.gov/boardDocs/speeches/2002/20021121/default.htm

In 2002, Ben Bernanke told us that a diligent Federal Reserve has all of the tools necessary to stop deflation.  Many have forgotten his speech. They think the Fed is "out of ammunition".

The most familiar stimulus is low interest rates. The Fed has used and continues to use that tool.

The next, the purchase of Treasury Bonds, known as QE2 has been used--it is being maintained, but not expanded.

Low rates and QE are like rocks and slingshots. The Fed has a large arsenal of many other, MUCH MORE POWERFUL tools.

Less familiar, but much more powerful tools remain to be used. I believe the next most powerful is the purchase of private debt securities and foreign debt securities. Finally, in my opinion, the most powerful: purchase of domestic and foreign equities.


No doubt, these tools will be used reluctantly. Given Rick Perry's warnings, monetary stimulus for "political" reasons would not be acceptable. However, the Fed's mission is "price stability" which includes controlling BOTH boom induced inflation and recession induced deflation. This has nothing to do with politics--it has to do with The Fed following their mandate. 

No doubt, all of this is "printing money" and is inflationary. That's the point. To kill deflation or fears of it, the Fed uses tools to create an offsetting or counteracting inflationary force.  The Money Supply is only part of the equation. Increasing the supply of money in an economy where money is "lazy" may only offset the deflation caused by the slow movement (velocity) of money through the economy.  Failure to print more money in such an environment would be the same mistake the Fed made in the 1930's.  They are not likely to make the same mistake this time--no matter what the politics.

Recessions are caused by collapsing asset bubbles or fear driven collapse in demand. They result in the slowing of money velocity. Before the Fed, the only thing you could do is hope that people would get over their fear sooner than later. The Fed's tool box gives it the ability to counter this slowing with a larger supply of money--either preventing the recession or making it shallow and of short duration.

Mr. Bernanke is well aware of the politics of 1937 and 2011--I think those who bet against him doing the right things are making a bad bet.

More analysis of the this subject is available by reading:


This paper is for educational purposes and for the sake of discussion. It is not a sales presentation and not a recommendation or personal investment advice. Opinions provided are exclusively those of Wayne Strout and are not the opinions by any financial institution. All investing involves significant risk of loss and there is no proven method to eliminate that risk. No investment should be made without a complete due diligence process, fundamental analysis and a discussion with your personal financial advisor.


Friday, August 19, 2011

What Next? Is it like 2008 or 2010?


Over the past 60 days, it has been hard to predict the direction of markets for the next day, let alone forecast where markets will be 30 days in the future. Uncertainty and volatility has been extreme. The S&P 500 has fallen 17% from it’s peak in April.

Last year, in 2010, we saw a similar pattern, with uncertainty about European debt and continued high unemployment in the US driving fears of a double dip recession. The S&P 500 fell 17% from it’s peak in April 2010 before rising 33% to the April 2011 peak.

So are we going into a recession or can we expect another 33% gain in the next few months?

In June, I introduced you to the Citigroup Economic Surprise Index. It can be viewed at Bloomberg http://www.bloomberg.com/apps/quote?ticker=CESIUSD:IND#
(under the ticker CESIUSD:IND ) A negative reading of the Economic Surprise Index suggests that economic releases have on balance failed to meet consensus expectations and have “disappointed”. This indicator reached an extreme low on June 3, improving since, but still with a negative reading. The debate about the debt ceiling and brinksmanship of the US government was shocking. The downgrade of the US by S&P was also shocking.  It seems like every talking head and prognosticator has felt the need to go on the record predicting a "possible" recession: 20%, 30%, 50% Chance.  NONE OF THEM KNOW!  (Remember, news media maintains your attention with stories meant to stir your emotion.)

The Federal Reserve QE2 stimulus ended in June. The debt ceiling debate reduced the likelihood of any government fiscal stimulus. In other words, this time, it looks less likely that the US government will, or even can, ride to the rescue of the economy. The really big deal is Europe.

In the US, banks lent too much money to individuals with mortgages. In Europe, banks lent too much money to governments. The individuals had at least some collateral.  Loans to governments are more dangerous--sort of like signature only loans with no collateral.  Too much “tough love” and “austerity” in Europe to reduce this government debt may result in a economic contraction there—a real recession that then might spread all over the world. Concurrent reduction of stimulus by the US Government actually increases the risk.

What many fail to appreciate is that while the end of QE2 ends the increase of Fed stimulus, the Fed is not withdrawing stimulus. Zero Interest Rate Policy (ZIRP) is in place for two more years and the QE balance sheet is being “maintained”. And, while clearly there will be reduction in deficit spending, the US will still be stimulating the economy with deficit spending higher than any time in history except for 2009-2011.  Franklin Roosevelt would never have even dreamed that it was possible for the US Government to throw so much money at the problem. Those that claim the war brought us out of the Great Depression should remember that the US is presently waging two wars.

As most of my clients already know, I study and monitor certain economic data that I call Reasonably Reliable Leading Indicators. While there are some economic indicators pointing to a slower economy, AT THIS TIME, none of what I deem to be Reasonably Reliable Leading Indicators are showing a pending recession. Retail Sales do not show signs of a pending recession. Industrial Production data does not show signs of a pending recession. Corporate Earnings Guidance indicated an expected slowing, but not a pending recession. The Interest Rate Yield Curve is still very steep. Unlike almost every recession in history, corporate bonds are rising or maintaining value as stocks have fallen—a bullish sign that indicates the recent market action is probably just an old fashioned panic and crisis of uncertainty.  When a real recession is likely, people typically sell corporate bonds and stocks at the same time.

Certainly the risk regarding Europe is significant—a lot will depend on the resolve of Germany and how much they are willing to give up in order to bail out the banks that lent too much to Spain, Italy, Greece, and Portugal. Let's hope the ECB stops raising interest rates and learns how to implement intelligent monetary policy.

Again, markets are determined by fundamentals and sentiment. Fundamentals (corporate earnings) are strong. (See graph) We invest in companies. Not only are companies profitable—they have accumulated cash and most have real “staying power” to survive downturns. This is not 2008. It is also probably not 2010 either.

Please remember that sentiment changes rapidly based on current news and information. What we don’t yet know, we don’t know. As I have stated “Life has been uncertain, difficult and dangerous. Uncertainty, difficulty and danger will continue to exist.”

It is very possible that the worst case scenario is already priced in. A 17% drop is a significant correction. (We are also down 28% from the 2007 highs. Some would argue that we are still in a recession--it hasn't ended yet.) History teaches, and indicators tell us that there is a possibility of further declines; But, there is a higher probability that markets will turn back up or at least stabilize. The biggest danger is probably fear itself where fear and resulting collective actions to avoid potential losses actually creates the economic slowdown that people fear and are tryiing to avoid. Emotion is the economy's (and your money's) worst enemy.

In times like these, it is important that any money invested is truly long term—then these short term up/down movements are much less important to you. It is also important to keep the emotions of fear and greed out of your thoughts as these emotions generally lead to bad decisions. Keep your mind on what you believe the companies you own, or want to own will be worth in 2-3 years from now—that is what investors do. Let the foolish speculators spend their energy on what the markets will do in the short term.  Keep in mind: long term investors make money; speculating is a zero sum game.


This paper is for educational purposes and for the sake of discussion. It is not a sales presentation and not a recommendation or personal investment advice. Opinions provided are exclusively those of Wayne Strout and are not the opinions by any financial institution. All investing involves significant risk of loss and there is no proven method to eliminate that risk. No investment should be made without a complete due diligence process, fundamental analysis and a discussion with your personal financial advisor.


Friday, June 24, 2011

Worried about Greece?


I don’t often write commentaries on a daily basis, but the developing saga and fear based market moves related to the current Greek credit crisis deserves your attention and a bit of understanding.

It is estimated that the total amount of Greek debt is well above $300 billion. That would make a default there one of the largest in history for one country. Larger than Argentina in 2002. And, Greece is not the only European country that has more debt than it can repay. It is a big deal.

Defaults like this (but not necessarily this large) however are not as uncommon as the average person thinks. Between 1998 and 2004, there were 15 governments that defaulted on their debt. Between 1976 and 1989, there were more than 40!

One of the things that I thought we learned in the past is that in most cases, by the time default is contemplated, the situation is usually so bad that a large part of the loans need to be written off. Here are some quotes from the EMTA’s site (link below) “The Brady Plan, the principles of which were first articulated by U.S. Treasury Secretary Nicholas F. Brady in March 1989, was designed to address the so-called LDC debt crisis of the 1980's…..From 1982 through 1988, debtor nations and their commercial bank creditors engaged in repeated rounds of rescheduling and restructuring sovereign and private sector debt, in the belief that the difficulty these nations experienced in meeting their debt obligations was a temporary liquidity problem that would end as the debtor nations' economies rebounded. However, by the time the Brady Plan was announced, it was widely believed that most debtor nations were no closer to financial health than they had been in 1982, that many loans would never be entirely repaid, and that some form of substantial debt relief was necessary for these nations and their fragile economies to resume growth and to regain access to the global capital markets.” Read more at the site:


What I thought we learned from past was that some sort of market based solution is necessary. Repackaging and reselling the debt. Something similar to the Brady Plan has been proposed by Daniel Gros, Director of the CEPS and Thomas Mayer, Chief Economist of Deutsche Bank. You can download their plan at the link:


One thing that is different this time is that those same pesky Credit Default Swaps we learned about during the mortgage bond credit crisis here in the US are involved in this crisis too! Seems like the French and German banks bought “insurance against default” on Greek, Irish and Portuguese debt—from US banks! So, it gets a bit more complicated. And, it is logical that a possible and probable default in Greece is creating a “not this again” fear in stock markets. i.e. 2008 all over again.

What is probably different however is that companies have prepared for this storm with strong balance sheets. And, hopefully, the US banks have prudently “reserved” for losses from their CDS "insurance" they have issued, with more capital. The Greek people vote on June 29 and June 30 on whether they will accept more “austerity”—a condition placed by lenders for more “bailout” money. It appears that markets are getting ready for the possibility that they will refuse and the crisis escalates. (Think Wisonsin.) Be prepared for volatility, risk and great uncertainty in this case. My best guess is that a temporary solution will be implemented, and then, sooner or later, the losses will be recognized and the crisis will end. We are at the end of the beginning of a resolution. I think this issue will be in the news for quite some time. I do not think that this week’s actions will merit any major portfolio changes, yet, as markets are likely to snap back very quickly. Be sure all of your present investments are long term oriented--the bottom of this may be a very good entry opportunity.


This paper is for educational purposes and for the sake of discussion. It is not a sales presentation and not a recommendation or personal investment advice. Opinions provided are exclusively those of Wayne Strout and are not the opinions by any financial institution. All investing involves significant risk of loss and there is no proven method to eliminate that risk. No investment should be made without a complete due diligence process, fundamental analysis and a discussion with your personal financial advisor.


Thursday, June 23, 2011

Borrowing Money is Fun! Paying it back--Not so much.


Graph of Household Debt Service Payments as a Percent of Disposable Personal Income
Ben Bernanke (06/22/2011).......“We don’t have a precise read on why this slower pace of growth is persisting,” Bernanke said. Referring to “frustratingly” slow job growth and weakness in the financial and housing industries, Bernanke said “some of these headwinds may be stronger and more persistent than we thought.”

You have got to hand it to a man who is honest and straightforward, but markets get spooked when the man who “should know what to do” tells us that the Fed does not know why growth is so slow and that they underestimated the headwinds holding back the economy. Add this to continued worries about the fiasco in Greece and it is no wonder that markets trend down.  (Remember that markets are driven by fundamentals and sentiment.)  Mr. Bernanke is a good man and a great economist--perhaps he is not the best at inspiring confidence.

The chart above is one illustration of the biggest problem: Too much debt and the consequences of debt reduction. Borrowing money is fun—paying it back—not so much fun. (Sort of like gaining and losing weight.) Households in the US took on too much debt—in fact you might say we went on a debt binge from 1994 until 2008. Since then, we have been paying off debt—fast and furiously! The good news—we are rapidly approaching a “sustainable” level of 10-11% of our income.

Oil prices had been rising rapidly for a year. But, recently they changed direction and have been falling. Today, the US and other nations agreed to release a lot of oil from strategic storage reserves. This will tend to accelerate the drop in the price of oil and is a big stimulus to global economic growth.

The one thing out there that is not necessarily “about to turn the corner” with certainty is the debt problem in Europe. Banks lent too much money to homeowners in the US. In Europe, banks lent too much money to governments. When a homeowner can’t pay the loan back, there is at least some collateral that can be sold in a foreclosure. Lending to governments is like a signature only loan or credit card debt—you can’t exactly foreclose—your only collateral is government revenue from taxes. When governments continue to run deficits, spending more than they take in from taxes, there is no surplus left to pay back the loans.

So, the problem in Greece specifically and with European government debt in general is yet to be resolved. I have no sure idea what the final outcome will be, but my understanding of history (specifically in Latin America) tells me that a great deal of the debt in Greece, Ireland and Portugal will have to be written off and restructured. Will that hurt the stock market? In the short run—you are seeing it today as this scenario is being “priced in”. In the long run, reducing debt and getting back to being “fit and trim” economically is probably very good for the economy and the stock market.

This paper is for educational purposes and for the sake of discussion. It is not a sales presentation and not a recommendation or personal investment advice. Opinions provided are exclusively those of Wayne Strout and are not the opinions by any financial institution. All investing involves significant risk of loss and there is no proven method to eliminate that risk. No investment should be made without a complete due diligence process, fundamental analysis and a discussion with your personal financial advisor.